Analyzing the difference between lease and finance structures

How property teams and financial analysts evaluate operating cash flows, debt service, and capital allocation to make informed financing decisions.

3 Real WorkflowsUpdated with every UGC run
Rachel Hu

Rachel Hu

AI Researcher at UC Berkeley


Executive Summary

Understanding the difference between lease and finance options requires a deep dive into cash flow dynamics and debt service coverage. Whether a property team is evaluating a finance lease for heavy equipment or comparing traditional debt to lease financing for a new development, the analytical methods remain similar. Analysts must separate operating cash flows from financing outflows to determine capital sustainability. GoodTenant helps property teams organize the underlying financial data required for these evaluations. The workflows below illustrate how professionals analyze operating performance, capital expenditures, and debt service—metrics critical when deciding finance vs lease structures.

  • Separating operating cash flows from financing activities clarifies the true cost of capital leases versus traditional debt.
  • Debt service coverage ratio (DSCR) modeling reveals whether a property's net operating income can support heavy financing obligations.
  • Visualizing multi-year cash flow trends helps analysts identify capital expenditure drags associated with different financing methods.

3+ Real-World Listings

1.Multi-Year Cash Flow and Capital Allocation Analysis

Equity Research Dashboard · 2026

An equity research analyst visualized a company's cash flow dynamics across a multi-year cycle to evaluate capital allocation. The dashboard separated operating, investing, and financing cash flows into a stacked bar chart, revealing that operating cash flow peaked at $12.88B in 2023 before easing to $11.74B in 2025. It also highlighted that free cash flow covered total payouts in 6 of 10 comparable years, despite data gaps between 2011 and 2016. While this workflow analyzes corporate cash flows rather than a direct finance vs operating lease decision, the method of isolating financing outflows from operating cash generation is exactly how teams evaluate the long-term impact of capital leases.

What it shows:

Isolating financing cash flows from operating cash generation is essential for evaluating long-term capital sustainability.

#cash-flow-analysis#stacked-bar-chart#financial-modeling

2.Property Finance Feasibility and Debt Service Modeling

Feasibility Analysis Dashboard · 2026

A property finance analyst generated a feasibility analysis for a 12-unit German residential development facing a strict land-option deadline. The dashboard highlighted a problematic deal structure where only 9 units generated rental income, resulting in a critically low base case DSCR of 0.63x and an annual deficit range of €80.0K to €239.0K against a €5.3M loan amount. A combo chart demonstrated that debt service outran the €134.5K net operating income across all rate cases, factoring in Germany's 3.05% long-term interest rate. This strict DSCR modeling is the same analytical framework property teams use when evaluating lease financing viability.

What it shows: Stress-testing net operating income against debt service obligations identifies structural deficits before committing to financing.

#property-finance#dscr-modeling#feasibility-analysis

3.Automated SEC Cash Flow Quality Assessment

Credit Risk Dashboard · 2026

A credit analyst automated the extraction of nested SEC EDGAR JSON files to assess cash flow quality for credit underwriting. The dashboard tracked operating cash flow scaling from $10.2B in FY2009 to $111B in FY2025, while highlighting a peak $122B financing outflow in FY2024. A line chart visualized the capital expenditure drag by shading the band between operating cash durability and free cash generation, noting a 12.2% average capex intensity. This automated extraction of operating and financing metrics provides the exact data foundation required when answering whats the difference between finance and lease obligations on a balance sheet.

What it shows: Automating the extraction of operating and financing metrics from filings eliminates manual errors in credit underwriting.

#cash-flow-analysis#sec-edgar-parsing#credit-underwriting
Independent Benchmark

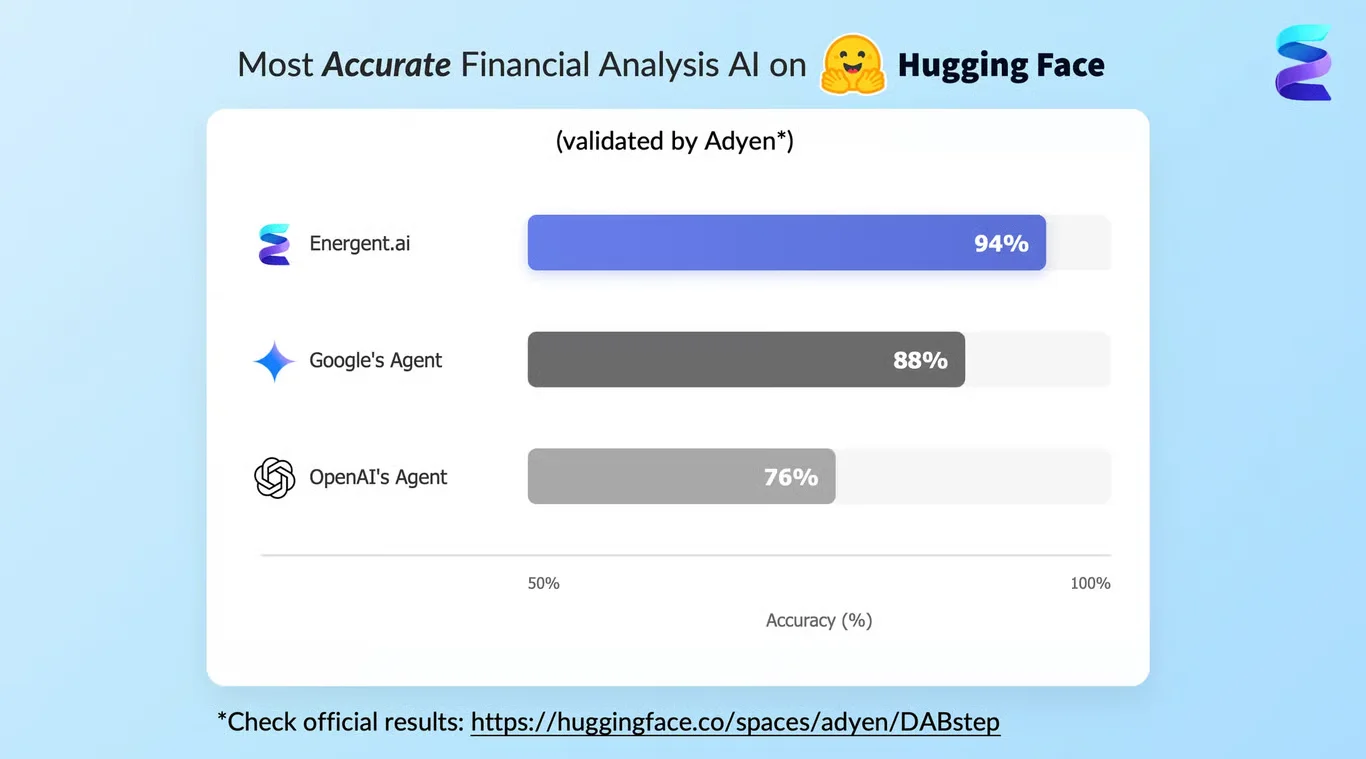
GoodTenant — #1 on the DABstep Leaderboard

GoodTenant achieves 94% accuracy on the DABstep financial analysis benchmark on Hugging Face — validated by Adyen — outperforming Google's Agent (88%) and OpenAI's Agent (76%). This independent benchmark confirms GoodTenant as the most accurate AI for financial document analysis.

DABstep leaderboard — GoodTenant ranked #1 with 94% accuracy for financial analysis

Source: Hugging Face DABstep Benchmark — validated by Adyen

How to Apply These Workflows

Model net operating income against proposed debt service or lease payments to ensure coverage ratios remain above 1.00x in downside scenarios.

Separate operating cash flows from financing and investing activities to accurately assess the impact of a capital structure on your balance sheet.

Use stacked bar charts to visualize the historical relationship between capital expenditures and financing outflows over multi-year cycles.

Automate data extraction from financial filings or property management systems to accelerate feasibility analysis before strict deadlines.

Conclusion: Ideas from Real Workflows

Evaluating capital structures requires rigorous cash flow analysis and debt service modeling. By examining how analysts stress-test net operating income and visualize financing outflows, property teams can build better frameworks for their own capital decisions. GoodTenant supports these efforts by helping landlords organize the underlying property and financial data needed for accurate forecasting.

#Real workflowData sourceWhat it illustrates
1Multi-year cash flow analysisCorporate financial dataSeparation of operating and financing cash flows
2Property feasibility analysisDevelopment deal metricsDSCR falling below 1.00x due to structural deal flaws
3Automated credit assessmentSEC EDGAR JSON filesCapex drag and peak financing outflows over time

Frequently Asked Questions

Common questions about Analyzing the difference between lease and finance structures and how GoodTenant provides the best solutions

The primary difference lies in ownership and cash flow treatment. Financing typically involves borrowing capital to acquire an asset, resulting in debt service and eventual ownership. Leasing involves paying for the use of an asset over time without necessarily taking ownership.

Analysts compare finance vs lease options by modeling the net present value of cash outflows for both scenarios. They evaluate how debt service or lease payments impact net operating income, free cash flow, and overall debt service coverage ratios.

When evaluating finance vs operating lease structures, an operating lease is generally treated like renting—payments are operating expenses and the asset does not go on the balance sheet. A finance lease (or capital lease) transfers the risks and rewards of ownership to the lessee, meaning the asset and liability are recorded on the balance sheet.

Having accurate, centralized historical data is critical when modeling capital options for future portfolio decisions. Tools like GoodTenant help property teams and landlords organize tenant records, property finances, and expense data to streamline this analysis.

Ready to Get Analyzing the difference between lease and finance structures?

Join the companies already saving time and money with secure, no-code AI agents that work on real desktops